In a subrogation Georgia personal injury case, subrogation lets your health insurer demand repayment from your settlement money. When you get hurt, your health insurer pays your doctors for care. Later, you receive a personal injury settlement from the party at fault. Your health plan then asks for that money back. They send a notice of a health insurance lien or a subrogation claim. Seeing that bill feels scary when you are trying to heal. This guide explains your rights under Georgia law. You will learn steps to keep your cash.

What Subrogation Actually Means in Georgia
How Health Insurance Subrogation Works
Subrogation is a contractual right included in most health insurance policies across the state. It allows your healthcare carrier to step into your financial shoes after an accident. When a negligent driver crashes into your vehicle, your health plan covers your initial emergency room bills. Once you resolve your claim, your insurer demands reimbursement from your payout. They argue that they should not pay for injuries caused by another driver. I see this situation every week at Jamie Ballard Law in Atlanta. Clients often feel confused when they receive repayment demands in the mail. Understanding how a subrogation Georgia personal injury dispute operates helps you protect your hard-earned financial recovery.
Your health insurance policy is a contract between you and your plan provider. That contract contains specific clauses about third-party recoveries. When another party causes your harm, your plan reserves the right to seek reimbursement. However, that contractual right is not absolute or unlimited under state rules. Insurers must follow specific procedures before taking funds from your recovery check. Many policyholders assume they must pay every dollar demanded right away. That assumption is wrong, and paying without review wastes valuable funds.
Why Insurers Claim Money From Your Settlement
Health insurance corporations monitor personal injury claims through automated tracking systems. They flag high-dollar hospital claims and emergency treatments stemming from motor vehicle collisions. When their systems detect third-party fault, they assign collection agencies to pursue reimbursement. Insurers argue that paying for your treatment while you retain cash creates an unfair windfall. In truth, injured crash victims rarely receive extra cash after paying for off-work time and pain. Insurers assert insurance company rights to grab funds before you pay rent or credit cards. Handling a subrogation Georgia personal injury demand requires analyzing every line item they present against your proceeds.
- What it is: your health insurer claims part of your settlement
- Who can claim it: private insurance, Medicare, Medicaid
- How much they take: the exact amount they paid for injury treatment
- Can you reduce it: yes, the made whole doctrine can help
The Difference Between Subrogation and Direct Medical Liens
Many injury victims confuse subrogation with a statutory health insurance lien filed by a hospital. A medical lien is a formal legal claim recorded in county court records. A lien attaches directly to your legal claim or monetary recovery by operation of law. Subrogation is a private contractual right written inside your health policy booklet. Both methods aim to take cash from your final personal injury settlement. However, statutory liens must comply with strict filing deadlines under Georgia Code. Contractual subrogation demands depend entirely on specific language inside your plan contract. Identifying which claim type you face shapes your defense strategy.
Hospital liens follow rigid statutory rules set by state lawmakers. If a hospital fails to file its lien on time, the lien becomes invalid. Subrogation claims do not require court filings to exist, making them harder to spot early. Your health insurer simply relies on policy language to demand reimbursement. Treating these two claims differently is essential when managing your accident recovery. Resolving a subrogation Georgia personal injury claim requires a deep review of policy language and plan structures.
Subrogation Type Comparison Guide
Understanding how different healthcare plans handle subrogation helps you anticipate payment demands. The table below compares major plan types, applicable laws, notice rules, and common negotiation strategies under Georgia law.
| Plan Type | Governing Law | Made Whole Rule Applies? | Typical Negotiation Strategy |
|---|---|---|---|
| Private Fully-Insured Plan | Georgia Insurance Code | Yes (O.C.G.A. § 33-24-56.1) | Assert Made Whole doctrine to eliminate payback demands entirely. |
| Self-Funded ERISA Plan | Federal ERISA Law | No (Preempted by federal law) | Audit plan documents, dispute non-accident charges, and negotiate fee deductions. |
| Medicare (Part A & B) | Federal Secondary Payer Act | No (Federal statutory super lien) | Request conditional payment summary, audit items, and apply statutory fee formula. |
| Georgia Medicaid | Georgia State Statute | No (Statutory lien) | Submit reduction request based on comparative fault, fees, and total damages. |
| FEHBA (Federal Employees) | Federal Employees Health Benefits Act | No (Federal contract preemption) | Verify contractual language and request administrative compromise for hardship. |
| TRICARE (Military) | Federal Medical Care Recovery Act | No (Federal statutory right) | File formal hardship waiver request with regional judge advocate office. |
How Georgia Statutes Control Payment Demands
State statutes place clear boundaries on how private insurers collect cash from injury victims. Georgia lawmakers created statutory protections to prevent unfair reimbursement demands against crash victims. Private health plans governed by state law must follow strict statutory limits. They cannot simply grab cash whenever you receive a settlement check from an auto insurer. Georgia law mandates that health plans prove you were fully compensated for all losses. If your recovery fails to cover all your losses, their reimbursement demand fails completely. We enforce every statutory defense to block unlawful collection attempts.
Practical rule: Never assume your health insurer is automatically entitled to repayment without reviewing your policy terms first.
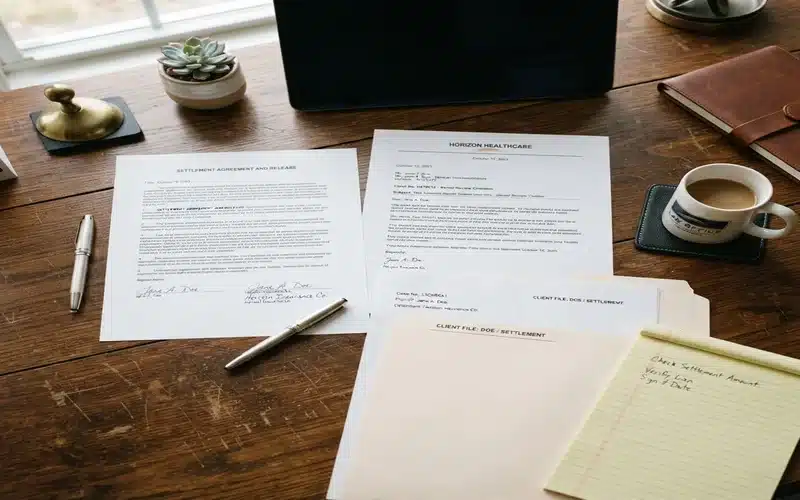
How Health Insurance Companies Claim Your Settlement
- You get hurt: your health insurance pays your medical bills
- You settle: you receive compensation from the at-fault party
- They want repayment: your insurer claims part of your settlement
- Negotiation: an attorney can reduce or eliminate their claim
Official Lien Notices Sent by Insurance Companies
The subrogation process typically begins when you receive an official notice in your mailbox. Subrogation vendors handle recovery operations for major health carriers across the state. They track police accident reports, ambulance logs, and hospital admissions. When they identify third-party fault, they mail a formal notice of a subrogation claim. This document demands that you notify them before signing any liability release. They ask for adjuster names, policy limits, and claim identification numbers. Receiving these formal notices creates real panic for crash victims in Atlanta. You should never ignore these legal notices or throw them away.
Private Group Health Plans and Policy Terms
Group health policies provided by employers contain detailed subrogation and reimbursement clauses. These contractual terms state that you must reimburse the insurer if you recover third-party money. They also prohibit you from taking any actions that prejudice the plan’s recovery rights. When you negotiate a personal injury settlement, the health carrier reviews your payout terms. They demand reimbursement for every doctor visit, therapy session, and prescription bill. Every subrogation Georgia personal injury dispute turns on whether policy language is explicit and enforceable under state rules. Ambiguous contractual phrasing can render an insurer’s payback demand completely unenforceable.
Self-Funded ERISA Plans and Federal Preemption
Self-funded employer health plans operate under federal ERISA regulations rather than state insurance laws. Federal ERISA law preempts state consumer protections for self-insured employer plans. If an employer pays healthcare claims directly from its own funds, ERISA governs the plan. ERISA plans frequently claim complete exemption from state buyer protection statutes. They demand dollar-for-dollar reimbursement from your settlement money regardless of your total losses. Determining whether a plan is fully insured or self-funded is a vital step in your case. We inspect plan summary descriptions to verify if federal preemption applies.
Practical rule: Always request an itemized payment log from your health plan to confirm every single charge.
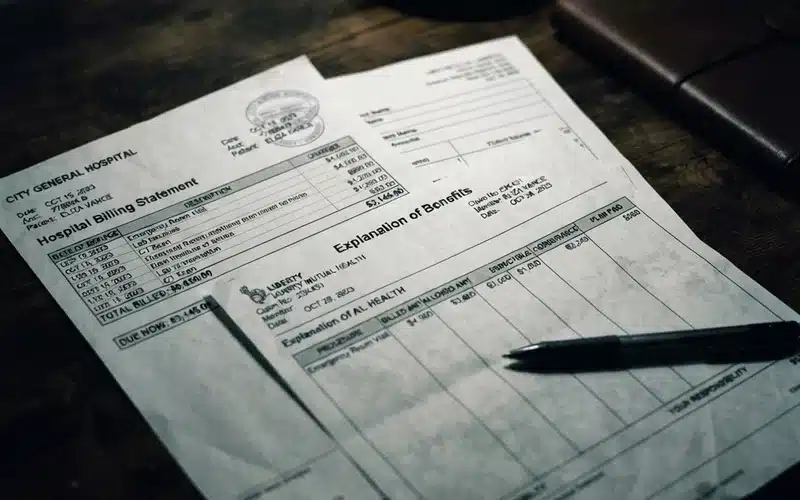 Hospital billing statement and insurance EOB form
Medicare and Medicaid Liens: Different Rules
Super Liens and Federal Medicare Recovery Rules
Government healthcare programs follow strict federal recovery statutes rather than standard contract law. Medicare holds a statutory super lien against all personal injury recoveries nationwide. Under federal law, Medicare receives automatic priority for repayment over other creditors. If you disregard a Medicare lien, federal authorities can file legal action against you and your attorney. Federal regulations allow the government to demand double damages for willful failure to reimburse Medicare promptly. You can read our detailed guide on how much Medicare takes from your settlement for deeper insights. Every subrogation Georgia personal injury matter involving Medicare requires strict compliance with federal reporting.
Georgia Medicaid Rights and Automatic Statutory Liens
Georgia Medicaid provides health coverage for eligible low-income families and disabled residents. Under state law, Medicaid obtains an automatic statutory lien on any personal injury recovery. The Georgia Department of Community Health oversees Medicaid recovery claims across the state. You can review official state healthcare resources on Georgia.gov for program details. Additional state Medicaid policy rules are published by the Georgia Department of Community Health. You can also review federal guidelines on Medicare.gov for related program rules. Medicaid claims must be settled before disbursing final funds to the client. We negotiate directly with state agencies to reduce Medicaid payback demands.
Reporting Your Injury Case to Federal Agencies
Handling federal healthcare claims requires strict compliance with federal administrative procedures. You must report your injury case to the Benefits Coordination and Recovery Center promptly. You can inspect official federal program rules at CMS.gov for Medicare compliance guidelines. CMS issues a conditional payment letter detailing all medical bills paid on your behalf. You must audit this list line by line to eliminate unrelated health treatments. After settlement, CMS sends a final demand letter stating the exact reimbursement amount owed. Following these administrative steps avoids severe penalties and protects your final recovery.
Practical rule: Federal Medicare liens always take priority and must be resolved before releasing funds to you.
Can You Reduce or Eliminate a Subrogation Claim?
Identifying What Bills Were Actually Paid
Health insurance collection vendors frequently include inaccurate charges in their subrogation demands. They routinely list treatments for pre-existing medical conditions or routine wellness exams. When managing a subrogation Georgia personal injury dispute, inspect every line item on the ledger. Confirm that every listed charge relates directly to injuries suffered in your motor vehicle accident. If a vendor includes unrelated care, demand its immediate removal from the total balance. Removing unrelated charges lowers the overall dollar amount claimed against your funds. Careful auditing keeps thousands of dollars in your bank account.
Deducting Attorney Fees and Case Expenses
Health insurance carriers should not benefit from your legal efforts without contributing to the cost. If you hire a lawyer to secure a recovery, your efforts benefit the health insurer. Under equitable legal principles, health plans must share the burden of legal representation expenses. Most private health plans agree to reduce their claims by one-third for attorney fees. They also deduct a proportional share of litigation costs, such as expert fees and court filings. Negotiating these standard reductions lowers the net health insurance lien significantly. You should never pay back full bill amounts without demanding fee reductions.
The common fund doctrine supports deducting legal fees from subrogation recoveries. This legal principle holds that a party who creates a fund for others must be compensated. Because your attorney created the settlement fund, the health plan must contribute to legal costs. Without your legal action, the health plan would receive no reimbursement whatsoever. Resolving a subrogation Georgia personal injury claim requires calculating exact proportional deductions for fees and litigation costs. Health plans routinely accept these standard deductions during settlement negotiations.
Negotiating Payment Terms Before Final Settlement
Never sign a liability settlement release before resolving all outstanding subrogation demands. Once you sign a release, the liability carrier issues funds directly to you or your attorney. If health plans demand full reimbursement later, you lose substantial bargaining power. You should negotiate with health recovery agents while settlement discussions remain active. Present evidence of limited policy coverage, liability disputes, or severe physical injuries. Health plans often accept reduced lump-sum payments to close files quickly. Securing written agreement protects your financial security after case resolution.
The Made Whole Doctrine in Georgia
Understanding Georgia’s Made Whole Statute
The Made Whole Doctrine is a powerful legal protection created by state lawmakers. Codified under Official Code of Georgia Annotated section 33-24-56.1, this statute sets clear boundaries. Under this law, an insurer cannot collect subrogation unless you are fully compensated for all losses. Full compensation requires receiving payment for all pain, lost income, and medical bills. If your settlement fails to cover your total economic and non-economic damages, the insurer gets nothing. This rule prioritizes the injured person’s financial recovery over corporate profits.
Georgia’s Made Whole statute was enacted specifically to protect accident victims from financial ruin. Lawmakers recognized that insurance policy limits are often too low to cover catastrophic injuries. When an at-fault driver carries minimal liability insurance, the victim suffers a net loss. In such cases, allowing a health insurer to take settlement cash causes severe hardship. Every subrogation Georgia personal injury matter governed by state law applies this made whole principle. The statute establishes that the injured victim must be made whole before the insurer receives a dime.
Proving You Were Not Fully Compensated
Establishing that you were not made whole requires thorough legal documentation and compelling proof. You must evaluate the true total value of your personal injury case. Calculate all past medical bills, future care needs, lost wages, and physical suffering. Compare that total case value to the total available insurance coverage. If a reckless driver carries minimum limits, your recovery falls far short of your losses. When total damages exceed available settlement money, you were not made whole under law. We build strong evidence packages showing why health plans cannot legally collect.
Shifting the Burden of Proof to Insurance Companies
Georgia law places the burden of proof squarely on the health insurance company. The health plan must prove that you were fully made whole by your settlement. They cannot simply allege full recovery without presenting clear evidence in court. If the insurer fails to prove complete recovery, their subrogation claim fails entirely. Recent decisions from the Georgia Court of Appeals confirm this strict legal standard. Most health insurers prefer not to litigate statutory damages issues in state courtrooms. This legal burden provides injured victims with immense bargaining strength during settlement negotiations.
The requirement that health plans prove complete compensation is a high legal barrier. Insurers must analyze every aspect of your injuries, treatment history, and financial losses. They must show that your settlement check fully satisfied every single head of damage. Because liability settlements usually represent a compromise, proving full compensation is extremely difficult. In a subrogation Georgia personal injury claim, if the insurer cannot satisfy this burden, courts dismiss their claim. We remind collection vendors of this strict legal standard during negotiations.
Practical rule: Under Georgia law, your insurer cannot collect a dime unless your settlement covers all your total losses.
What Happens If You Settle Without Addressing Subrogation
- Private health insurance: contract-based right to reimbursement
- Medicare: federal statutory right, very hard to reduce
- Medicaid: state program with mandatory repayment
- Workers’ comp: if the injury happened at work, different rules apply
Risk of Breach of Contract Lawsuits
Ignoring subrogation notices creates serious legal risks for injured policyholders. Your health insurance contract requires full cooperation during third-party recovery efforts. If you accept cash and ignore their demands, you breach your insurance contract. The insurance company can file a civil lawsuit against you for full reimbursement. They may seek court judgments, asset levies, or bank account garnishments. Hiring an experienced Atlanta personal injury lawyer prevents costly litigation. You must handle all valid claims before spending your settlement proceeds.
Loss of Future Health Insurance Coverage
Failing to repay valid subrogation claims can endanger your ongoing health coverage. Insurers may cancel your policy or refuse to pay future medical claims. They can offset future medical benefits against the unpaid subrogation balance. If you require ongoing care for crash injuries, unpaid claims create massive roadblocks. Doctors may refuse treatment if insurance claims are repeatedly denied by your carrier. Resolving every health insurance lien ensures continuous access to medical care when needed.
Losing health insurance coverage after a serious accident can have devastating health consequences. Ongoing rehabilitation, follow-up surgeries, and prescription medications require reliable coverage. If an insurer cancels your policy for non-cooperation, finding replacement coverage can be difficult. Resolving a subrogation Georgia personal injury dispute cleanly protects your policy standing and ensures unbroken access to care.
Potential Personal Financial Liability
Settling an injury claim without addressing subrogation leaves you personally liable for debt. Liability insurers often require you to indemnify them against health plan claims. If a health insurer sues the at-fault driver’s insurance company, that company turns to you. You could end up paying defense costs and judgment amounts out of pocket. Proper planning avoids unexpected financial disasters after signing settlement papers. Managing every subrogation Georgia personal injury matter carefully prevents unfair indemnification traps.
Practical rule: Resolving health plan claims during settlement negotiations prevents costly lawsuits and protected coverage losses later.
Subrogation Questions Answered
Here are answers to common questions injured victims ask about healthcare repayment demands and insurance company rights in Georgia.
| Question | Answer |
|---|---|
| What is a subrogation claim in Georgia? | It is a demand by your insurer to get paid back from your settlement money for accident medical care. |
| Does my health plan always have insurance company rights to my settlement? | No. Under Georgia law, fully insured plans cannot collect unless you are fully made whole for all losses. |
| What is a Medicare lien and how does it work? | It is a federal statutory claim that requires primary repayment from your personal injury settlement before funds disburse. |
| Can I negotiate a health insurance lien down in a subrogation Georgia personal injury case? | Yes. You can audit billings, deduct attorney fees, or assert statutory defenses to reduce or eliminate payback amounts. |
| What happens if I ignore a subrogation claim? | The insurer can sue you for breach of contract, drop coverage, or seek reimbursement directly from your settlement. |
| How does the Made Whole Doctrine protect my medical bills payout? | It prevents insurers from collecting reimbursement unless your settlement covers all economic and non-economic losses completely. |
| Should I pay off my medical bills before settling my case? | You should consult an attorney first, as paying bills early without negotiating can waste thousands of dollars in settlement money. |
How a Lawyer Handles Subrogation for You
Auditing Medical Records and Payment Ledgers
An experienced attorney starts by auditing every itemized medical ledger thoroughly. Health recovery vendors frequently include incorrect charges, duplicates, or non-accident treatments. We cross-reference medical records with billing statements line by line. We remove all charges paid for unrelated conditions or pre-existing ailments. This careful auditing process frequently reduces subrogation demands by thousands of dollars. Protecting your settlement money requires detailed attention to every single dollar claimed.
Challenging Illegal Health Plan Payback Demands
Not all subrogation demands are legal or enforceable under current law. We examine policy documents to verify if plans comply with statutory rules. If a plan is fully insured, we enforce Georgia’s Made Whole statute vigorously. If a plan claims ERISA exemption, we demand full summary plan descriptions. Many recovery vendors back down when confronted with strong statutory legal arguments. We draft formal demand letters, similar to our sample demand letter for auto accident cases, to enforce rights.
Maximizing Your Net Cash Settlement
Our primary goal is maximizing the net money that lands in your pocket. We do not just negotiate with auto insurance adjusters on liability. We fight equally hard to reduce every single Medicare lien and private claim. By reducing medical payback demands, we increase your final cash recovery significantly. You deserve every dollar possible to rebuild your life after a serious crash. We handle all communications, paperwork, and legal negotiations on your behalf.
Your net recovery is the only figure that truly matters when your case concludes. High settlement amounts mean little if health plans consume the majority of the proceeds. Every subrogation Georgia personal injury resolution focuses on protecting your wallet. By maximizing recovery and minimizing liens, we maximize your final cash payout. We provide transparent settlement statements showing every fee, expense, and lien reduction.
Keeping More Money From Your Georgia Injury Settlement
Taking Action to Protect Your Settlement Money
Managing subrogation demands is vital in any subrogation Georgia personal injury case. Never let health insurance companies take your money without a fight. By auditing records, asserting defenses, and applying Georgia law, you protect your personal injury settlement. If you face a subrogation claim, call Jamie Ballard Law today at (404) 885-8544 or visit our contact page. We will fight to protect your cash.